
Electronicseng Semiconductors Insight: Intel 18A Mass Production, 14A PDK Path and AMD Cooperation Signals
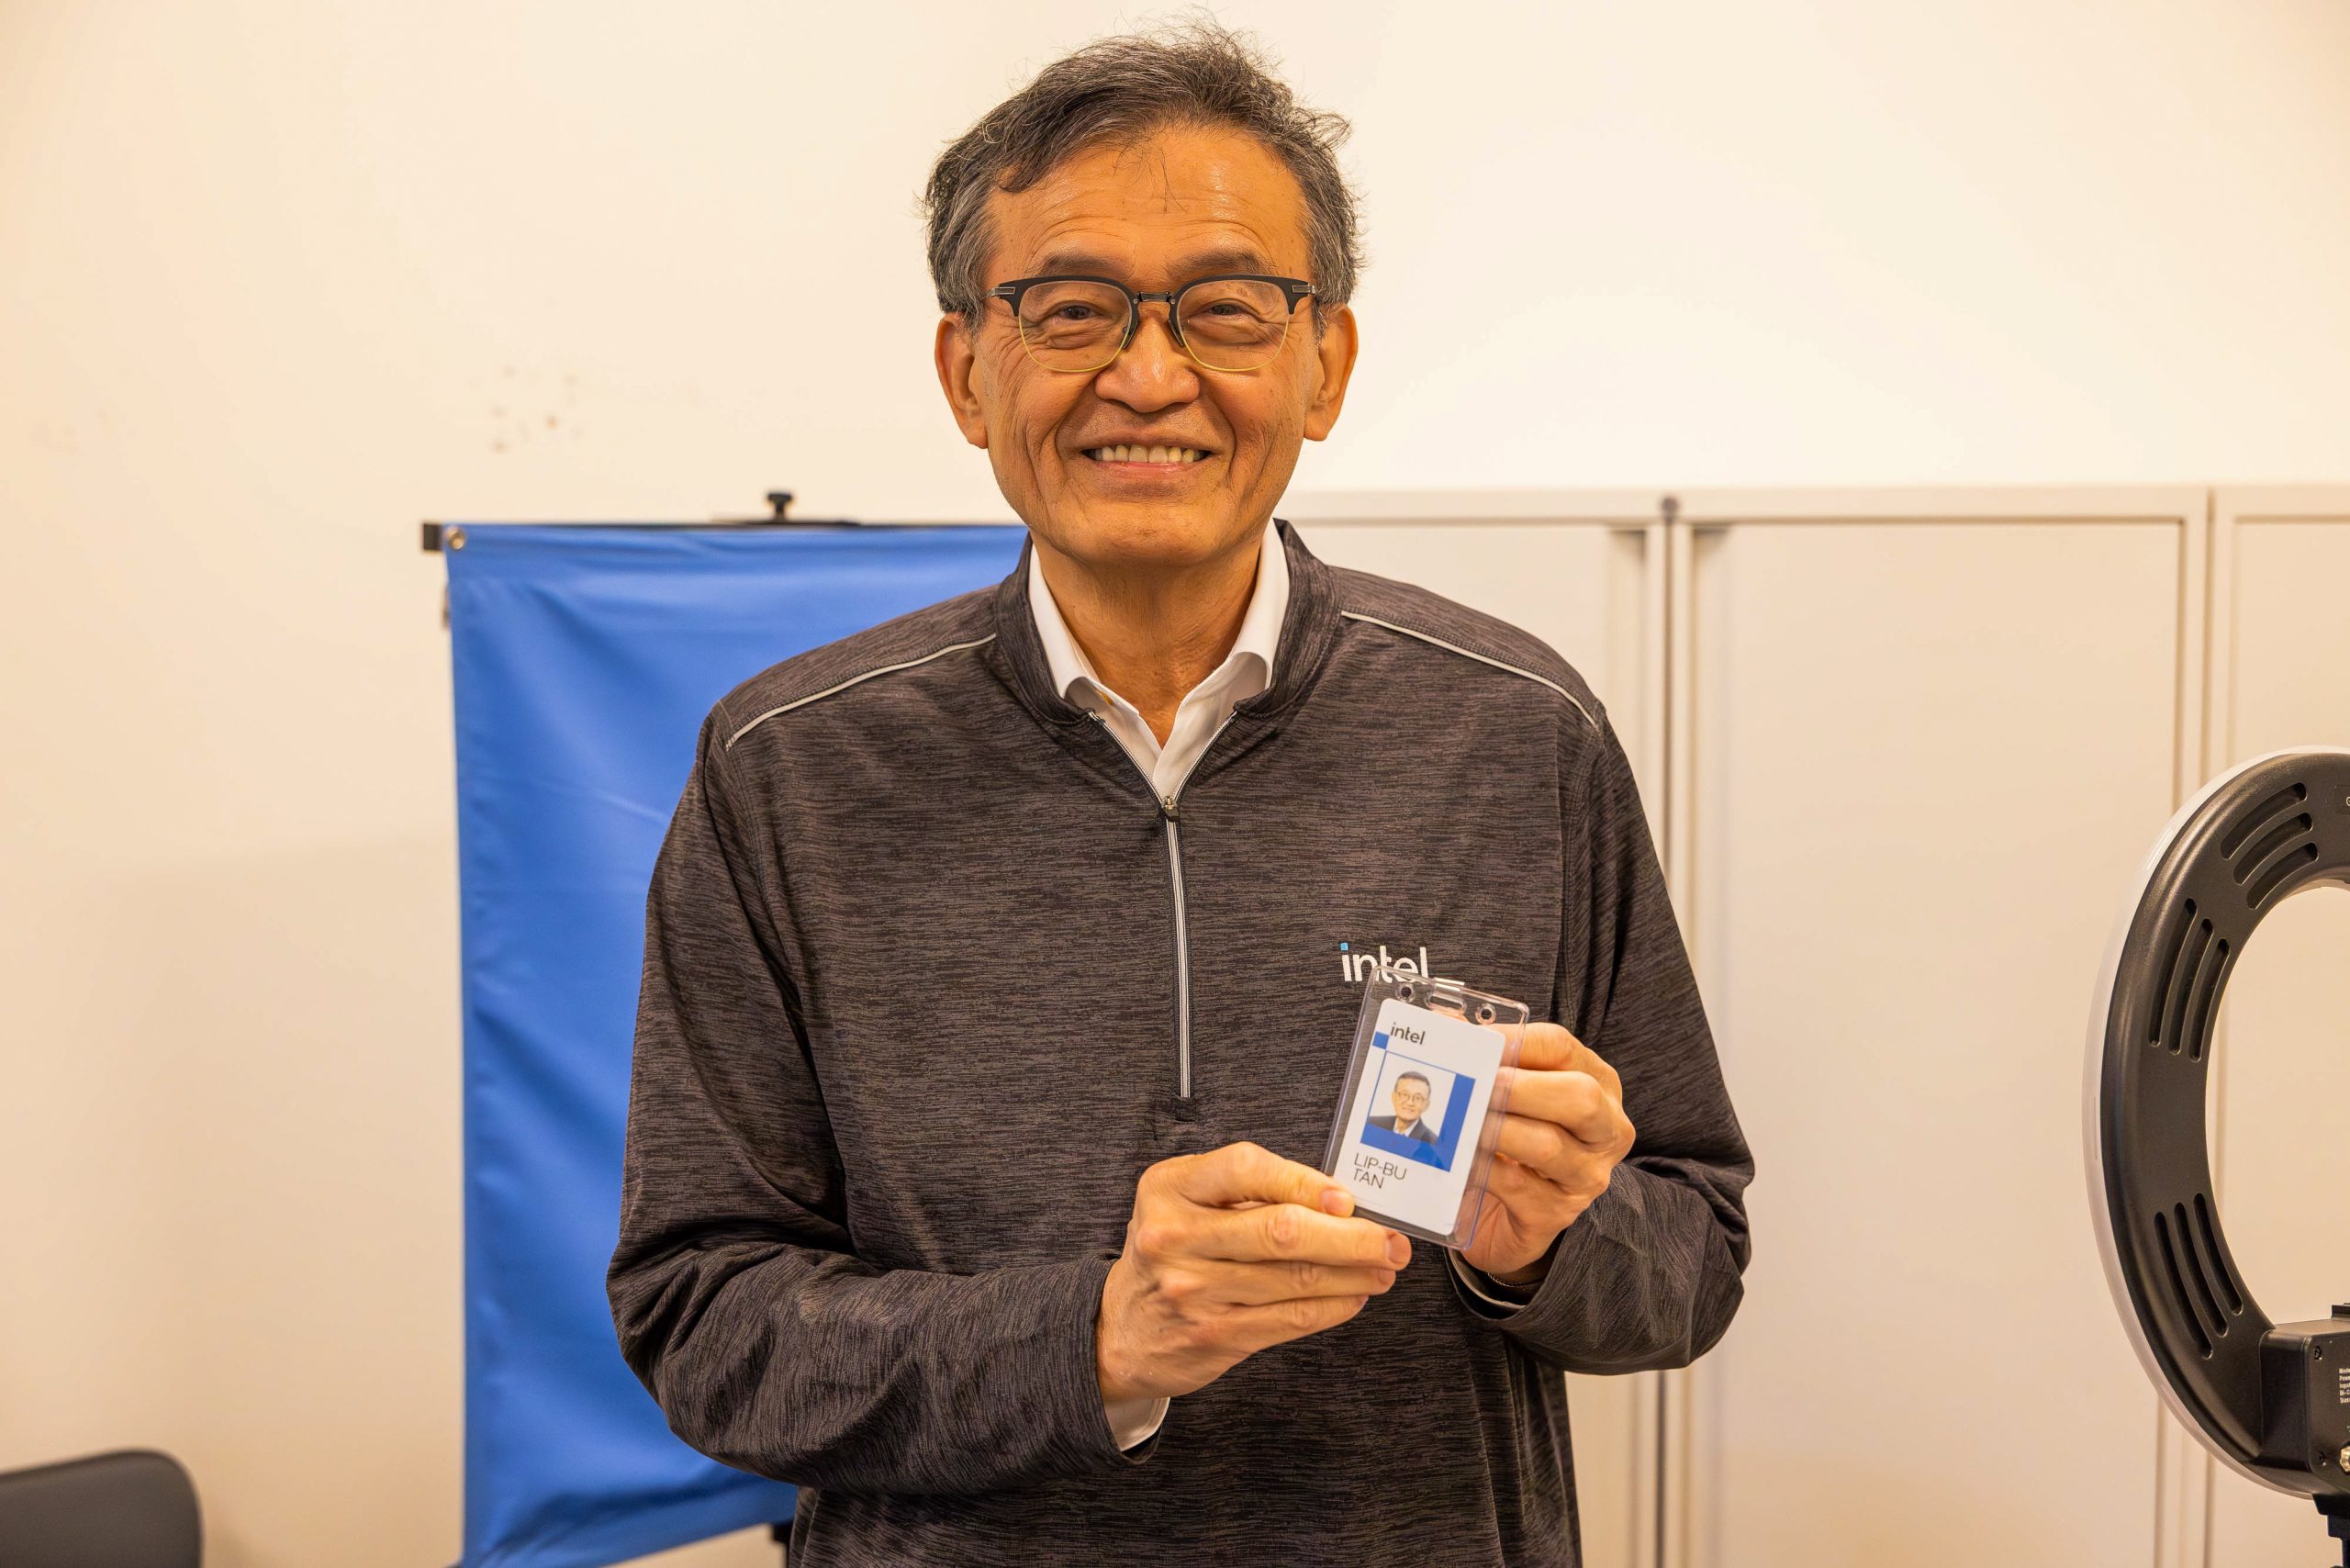
For electronics engineers, semiconductor researchers, hardware procurement teams and supply-chain analysts, the most useful takeaway from Intel CEO Lip-Bu Tan's recent CASPA discussion is not a broad industry claim, but a set of manufacturing checkpoints. Speaking on October 24 in a Chinese American Semiconductor Professional Association, CASPA, fireside chat, Lip-Bu Tan said Intel is competing for CPU performance leadership, has advanced 18A into mass production, and is preparing 14A for tape-out through staged PDK releases. He also said he has spoken with AMD Chairman and CEO Lisa Su about possible future cooperation, while a recent channel report from KeyBanc adds customer evaluations, packaging-yield data and several order narratives that remain unconfirmed by Intel or Apple official sources.
For the Electronicseng Semiconductors audience, the value of this update lies in separating confirmed manufacturing status from channel reports. The following sections translate the remarks and report into decision checkpoints for design, sourcing, packaging and supplier-management reviews.
Manufacturing Signals from the CASPA Session
Since Lip-Bu Tan took office, Intel has given concentrated attention to 18A and 14A, he said. 18A has already entered mass production, and progress on 14A is moving fast. Intel currently has a 0.5 version PDK for 14A, will release a 0.9 version PDK not long after, and plans to introduce a 1.0 version PDK in early next year to support formal mass production.
That distinction matters because a PDK is not a single product launch. In foundry terminology, a PDK, or Process Design Kit, is a complete set of design rules, models and technical documents supplied by a wafer foundry to a chip design company. The public version is a readiness signal: an early test release such as a 0.5 version usually indicates limited access for early evaluation; a 0.9 version means the process node has tape-out capability and can enter risk production, which is an important milestone before volume.
Lip-Bu Tan also discussed customer-facing behavior. He described a case in which one customer had waited 6 to 8 months and had hoped he would take over as Intel CEO. After a formal meeting, the customer listed 15 items tied to Intel's past problems. He said Intel management had sometimes behaved as if it were giving a lecture to customers instead of seriously listening to their needs. He then addressed each item and worked toward resolution, which eventually won the customer's trust and led the customer to decide to deepen its cooperation with Intel.
In parallel, the CASPA session placed AMD within Intel's strategic landscape. Lip-Bu Tan said he has communicated with AMD Chairman and CEO Lisa Su, and the two discussed fields where cooperation may become possible in the future. He did not disclose concrete collaboration directions, but the remark is significant because Intel and AMD have long been competitors in CPUs.
A Practical Checklist for Reading Intel's Foundry Roadmap
- Check whether a node is described as mass production, risk production, tape-out ready or PDK available.
- Read the PDK version number as a schedule signal: 0.5 version early test, 0.9 version tape-out and risk production readiness, 1.0 version intended for formal mass production in early next year for 14A.
- Separate statements made by Intel at the October 24 CASPA fireside chat from third-party channel information released recently by KeyBanc.
- Label each customer relationship as confirmed, reported but unconfirmed, or under evaluation.
- Treat advanced packaging yield reports as supplier-specific data, especially when Ibiden and UMTC are listed with different levels.
- Watch whether reported cooperation with AMD moves from conversation to defined scope.
Comparison Table: Node, Packaging and Channel Status
| Item | Public status in the reports | Classification for engineering or sourcing review |
|---|---|---|
| 18A | Has entered mass production. | Can be treated as an available advanced node for discussions about production readiness, assuming design rules, supply and package compatibility are confirmed. |
| 14A | 0.5 version PDK available; 0.9 version PDK expected not long after; 1.0 version PDK planned for early next year to support formal mass production. | Pre-volume roadmap node. Design teams should use PDK versioning to decide whether to access early test, prepare for tape-out and risk production, or wait for the volume-supporting version. |
| 18A-P | Being evaluated by potential customers including Amazon, Anthropic and SpaceX/Tesla Terafab; most customers are reported to be more inclined toward 14A. | Variant under customer evaluation rather than a broadly adopted target in the channel report. |
| Reported orders | KeyBanc says Intel has received foundry orders including production of network switch chips for Broadcom and server CPUs for Google; Microsoft server processors and Nvidia gaming GPUs are also reported to be made by Intel. | Channel information. Procurement and competitor analysis should confirm each order at official level before using it as a supply-chain assumption. |
| Apple narrative | KeyBanc suggests Apple has reached a long-term agreement with Intel covering multiple generations of M series and A series chip production, with 14A planned instead of the frequently rumored 18A-P. | Unconfirmed. Official confirmation has not been disclosed, and industry views differ. |
| EMIB-T substrates | Substrate production yield for Intel advanced packaging technology EMIB-T is reported at about 50% to 60%. Ibiden performs better, while UMTC is reported at 20% to 30%. | Supplier-specific packaging risk. Engineering teams should track substrate yield separately from wafer node yield. |
Data Citation
The facts summarized here come from two public types of sources: Lip-Bu Tan's remarks at the October 24 Chinese American Semiconductor Professional Association, CASPA, fireside chat, and a recent channel survey report from KeyBanc. The article does not add independent measurements, order confirmations or technical parameters beyond these reports.
Common Misconceptions
- Misconception: If Intel says 14A has a PDK, the node is ready for mass production. Correct reading: Intel has a 0.5 version PDK, with 0.9 version expected not long after and 1.0 version planned for early next year for formal mass production.
- Misconception: A reported customer list is the same as an official order. Correct reading: KeyBanc's recent channel report includes orders and evaluations, but the Apple agreement is not officially confirmed.
- Misconception: Packaging substrate yield is wafer fab yield. Correct reading: EMIB-T substrate yield at 50% to 60% for Ibiden and 20% to 30% for UMTC is supplier-specific packaging material data.
- Misconception: Talking with AMD means a confirmed business partnership. Correct reading: Lip-Bu Tan said he and Lisa Su discussed possible future cooperation fields, without disclosing specific directions.
- Misconception: The customer issue story is only management anecdote. Correct reading: the 6 to 8 months waiting period, the 15 items and the shift from lecture to listening are part of how Intel is describing its customer trust recovery.
FAQs for Engineers and Procurement Teams
What is the most concrete manufacturing update from the CASPA session?
The most concrete node update is the PDK sequence for 14A: 0.5 version PDK available, 0.9 version PDK expected not long after, and 1.0 version PDK planned for early next year to support formal mass production. 18A is separately described as already in mass production.
Why does the 0.9 version PDK matter for a 14A schedule?
Because 0.9 version is associated with tape-out capability and risk production. In this context, it suggests 14A is moving from early test toward a stage where design teams can prepare for risk production, while 1.0 version is the milestone linked to mass production support.
Are the Broadcom, Google, Microsoft and Nvidia items confirmed orders?
They are channel-reported items from KeyBanc. The report says Intel has secured orders such as Broadcom network switch chips and Google server CPUs, while Microsoft server processors and Nvidia gaming GPUs are reported to be produced through Intel. Teams should verify each relationship at official level if it affects procurement or competitive assessment.
What does the EMIB-T yield information indicate?
It indicates that advanced packaging supply is not uniform across substrates. The report gives substrate production yield around 50% to 60%, says Ibiden performs better, and places UMTC at 20% to 30%. For package-level planning, this is a supplier risk input rather than a general statement about 18A or 14A wafer output.
How should teams interpret Intel's contact with AMD?
As a signal that cooperation topics are being discussed, not as a confirmed collaboration. Lip-Bu Tan said he has communicated with Lisa Su and discussed fields of possible future cooperation, but he did not provide specifics.
Action Recommendations
- For semiconductor R&D teams, treat 18A as a production-ready reference point while building a 14A access plan around the 0.5 version, 0.9 version and 1.0 version PDK milestones.
- For hardware procurement and supply-chain planners, separate the KeyBanc channel report into three buckets: confirmed by Intel, channel-reported but unconfirmed, and customers evaluating 18A-P or 14A.
- For advanced packaging engineers, track EMIB-T substrate yield by supplier and model risk from the difference between Ibiden's 50% to 60% level and UMTC's 20% to 30% level.
- For competitive analysis teams, monitor whether the Intel-AMD conversation with Lisa Su develops into a concrete area, because the current information is limited to possible cooperation fields.
- For technical management, use the customer story-waiting 6 to 8 months, 15 items, lecture versus listening-as a checklist item for customer review processes: each customer concern should be logged, addressed and verified as resolved.
Conclusion: Manufacturing Readiness Is the Thread
The recurring theme is stage-gated readiness: 18A is in mass production, 14A is being sequenced through 0.5 version, 0.9 version and 1.0 version PDK releases, while customer interest in 18A-P and 14A, supplier-specific packaging yield and possible cooperation with AMD remain separate lines of evidence. For readers who need to make design, sourcing or analysis decisions, the practical next step is to track whether PDK versions, supplier yields and official order disclosures move from signal to commitment.